Retirement planning and investment management

Retire with a plan
for every dollar.

We help you turn what you've saved into a steady retirement paycheck, invest the rest with discipline, and keep the whole plan current as life and markets change.

Four questions every retiree asks
  1. How much can I spend each month?
  2. What happens when the market drops?
  3. How do I pay less in taxes?
  4. Will my money last as long as I do?
A good plan answers all four.
In writing, before you need the answers.
Held to the fiduciary standardYour advisor is required to put your interests first on the advice we give.
Your money stays in your nameAccounts are held at Charles Schwab, one of the largest custodians in the U.S.
One clear fee, with a capBilled from your advisory account each quarter. Nothing out of pocket, and no hidden charges.
No long-term commitmentYou can end our advisory services at any time, for any reason.
Who we help

Saving for retirement and living on it are two different jobs.

Most of the people we work with are getting close to retirement or already there. Wherever you are, the goal is the same: a paycheck you can plan around.

Five to ten years out

You're getting close.

The choices you make now about saving, taxes, and when to stop working shape the paycheck you'll live on. We build the plan while there's still time to adjust it.

Retiring soon

You're about to make the switch.

Turning a lifetime of savings into income is a different job than building it. We map out where each month's paycheck comes from, when to claim Social Security, and how to handle the first years of withdrawals.

Already retired

You want a second set of eyes.

Maybe the plan you started with no longer fits, or nobody is watching the taxes. We review what you have, keep what works, and bring the rest into one coordinated plan.

More than ten years out?

Put your savings in professional hands now.

You may not need a full retirement income plan yet. Your investments can still be professionally managed with the same disciplined approach we use for retirees, so the money you're saving today is working toward the day you'll need it.

A lower, management-only fee schedule is available.

Find your investment strategy
Investment management includes
  • A portfolio matched to your goals and timeline
  • Ongoing management and rebalancing
  • Investment advice whenever you need it
  • Unlimited access to your advisor
  • Clear reporting you can check any time
  • Coordination across your IRAs, Roth IRAs, and brokerage
  • Accounts held in your name at Charles Schwab
  • An annual review
Our approach

Most advisors pick a side.We are hybrid advisors.

Some advisors only manage investments. Others only sell annuities and life insurance. Most retirements need both, working together under one plan.
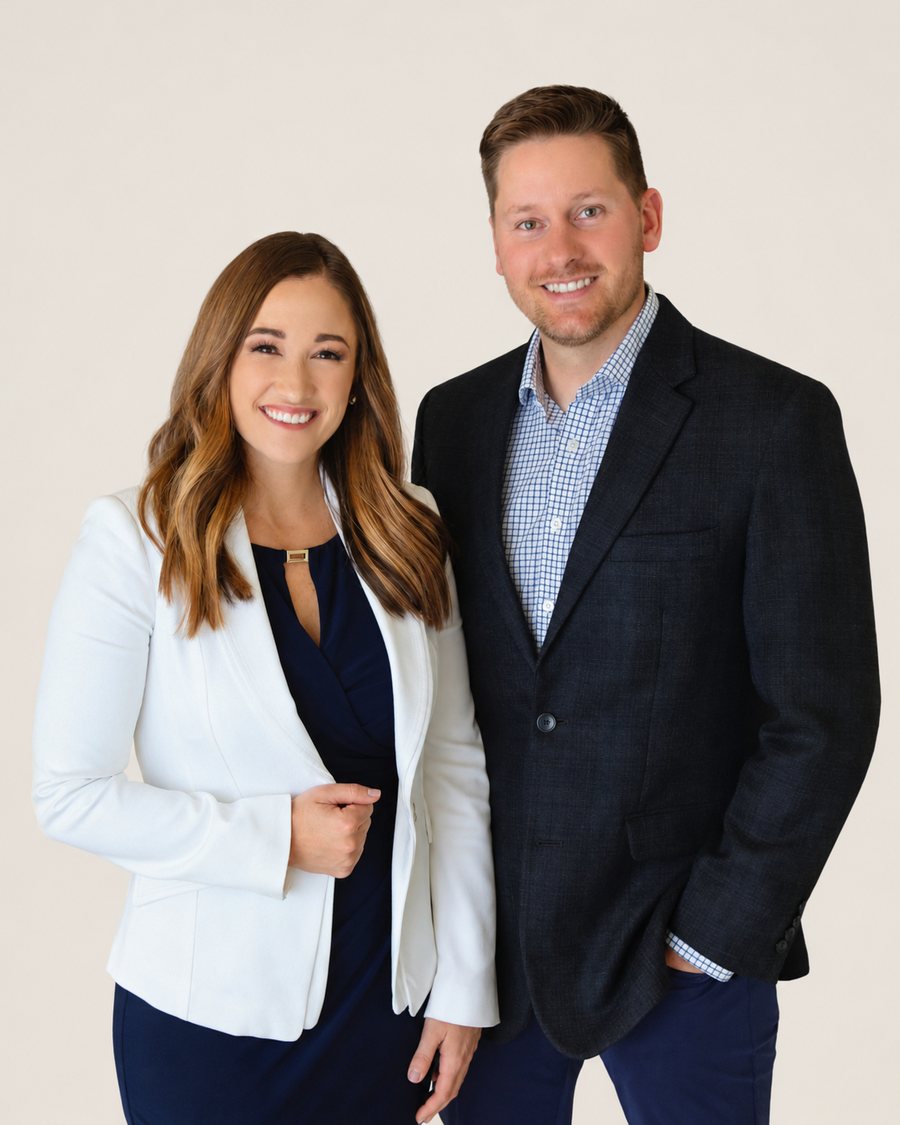
How we're paid
Sean and Megan Jantz, founders of Jantz Wealth Advisors
Sean and Megan JantzFounders of Jantz Wealth Advisors
Investment management

The engine of your plan

Diversified, low-cost portfolios managed for you. Rebalanced on a schedule, tax-aware, and matched to your risk tolerance and capacity.

Paid by an advisory fee. Deducted from your account. Nothing out of pocket.
Annuities and life insurance

The floor under your plan

Annuities and life insurance, used only where they solve a specific problem: covering essential expenses for life, cushioning market drawdowns, or protecting the people you love.

Paid by the insurance company. Disclosed before you sign.

The point is coordination. Your investments, annuities, and life insurance are chosen together, so each one does the job it does best and nothing is working against the rest.
The Retirement Stack

Every dollar should have a role.Every vehicle should have a job.

Your plan is built in four layers, from the bottom up. Each layer has one job, and each one is funded with the tool best suited to it.

Built from the bottom up. When your essential bills are covered by income that doesn't depend on the market, the money in your Growth Engine can stay invested through the drawdowns instead of being sold at the wrong time.

Tax-smart income

It's not just what you have.It's what you keep after taxes.

Every withdrawal has a tax cost. We plan which accounts you draw from and when, looking to lower what you pay over your lifetime, not just this year.

  • Roth conversions in lower-tax years
  • Managing Medicare IRMAA surcharges
  • Planning ahead for required minimum distributions
  • Keeping taxes on Social Security in check
  • Coordinating with your CPA
4

Legacy

Assets set aside for others

What you want to leave to family or causes you care about, positioned to pass on efficiently.

3

Growth Engine

Investment portfolio and growth annuities

Funds your lifestyle spending, keeps pace with inflation, and is managed to ride out market swings.

2

Guaranteed Income Floor

Lifetime income annuities, if needed

Closes any gap between your Foundation and your essential expenses, so the bills are covered for life.

1

Foundation

Social Security and pensions

The income you already have coming. We help you claim it at the right time, because it pays you for as long as you live.

Start here
How it works

Four steps.No pressure at any of them.

You'll always know where you are in the process and what comes next.

Watercolor illustration of a retired couple smiling at each other over coffee while reviewing papers at a kitchen table
1

A first conversation

A short, no-cost conversation about where you are, where you want to go, and whether we're the right fit for each other.

2

Your plan, in writing

We map your income sources against your expenses, test the plan against market drawdowns and inflation, and show you the paycheck it can support.

3

Put it to work

Accounts open in your name at Charles Schwab. Your investments go into the portfolio that fits you, and an annuity or life insurance is added only where it solves a problem in your plan.

4

Stay on course

Ongoing management, an annual review, and access to your advisor whenever you need it. When life or markets change, the plan changes with them.

The Global Core Portfolios

Four portfolios.One disciplined approach.

Five low-cost building blocks, in four mixes: U.S. stocks, dividend stocks, international stocks, short-term Treasuries, and gold.

Conservative

For steady income with the smallest swings.

40% stocks60% stability

Moderate

More growth, with a large stability sleeve.

55% stocks45% stability

Balanced

A middle path between growth and stability.

70% stocks30% stability

Growth

For longer time horizons and investors comfortable riding out drawdowns.

90% stocks10% stability
Stocks: U.S., dividend, and international Stability: short-term Treasuries and gold
Not sure which fits?

Take the Investment Strategy Assessment (ISA).

A short set of questions about your time horizon, your income needs, and how you react when markets move. Your answers point to the portfolio that fits you best.

It's a starting point for a conversation, not a final answer.

Take the assessment
Common questions

Straight answers
before you call.

Didn't see your question?

Ask it in a short conversation.

No cost and no obligation. No question is too basic.

Schedule a conversation
No. Jantz Wealth Advisors works with clients across the country. You can meet with your advisor in person where one is local, or by video from home. Most of the work happens the same way either way.
One clear advisory fee, starting at 1.50% a year on your first $500,000 and stepping down from there, with a cap of $20,000 a year. It's billed quarterly and deducted from your account, so there's nothing out of pocket. If an annuity or life policy is part of your plan, your advisor is paid a commission by the insurance company, disclosed before you sign. See the full fee schedule.
Generally, no. The questions that matter in retirement are the same whether you've saved a little or a lot: how much you can spend, what happens when markets drop, and how to keep taxes in check. No matter how much you've saved, an introductory conversation is worth having. At the very least, you'll leave with a clearer picture of where you stand.
No. An annuity is a tool, and it's only recommended where it solves a specific problem in your plan. The same goes for life insurance. When it is part of a recommendation, you'll see the alternatives we considered and the trade-offs of each before you decide anything.
Your investment accounts are held in your name at Charles Schwab. You can see every account and every trade in the Schwab app, and you receive statements directly from Schwab. Annuities and life insurance are held directly with the insurance company that issues them.
It's a short conversation, not a sales pitch. We'll ask about your goals, your timeline, and what's on your mind, and you can ask us anything. If it looks like a fit, we'll explain what the planning process looks like. If not, we'll tell you that too.
No. There's no long-term commitment. You can end our advisory services at any time, for any reason. Annuity and life insurance contracts have their own terms, which are explained in full before you sign.
The next step

See what your retirement paycheck could look like.

A short conversation is the fastest way to find out where you stand, and whether we're the right fit.

No cost. No obligation.